After Diwali: How to Normalize Festive Sales Before Valuing a Retail or D2C Business
Diwali is around the corner and if you are a retail brand running a business, then you would know the game plan. Sales orders will be coming in on every front, the warehouse will be in complete disarray, and the team will be running on a cup of tea and very little sleep. The moment the sales figures start climbing, it’s simply an incredible feeling to witness.
However, there is something that can really catch a few entrepreneurs by surprise. A few weeks later an investor or a buyer says, “can we get a company valuation done?” and right then your festive numbers will be sitting in your financial sheet, in the middle of the usual quarters, giving the look of a normal quarter.
They aren’t normal. And if no one makes a correction for festive effect, the valuation will probably wrong. Maybe overestimated, maybe underestimated, and in both cases it will fall apart the moment someone gets questioning it.
Therefore, let’s discuss what is a simple and effective way to normalize your Diwali sales before anyone puts a number on your business.. No need to overcomplicate it.
1. Why Festive Sales Distort Retail and D2C Business Valuation
Valuation is essentially the opinion of what a business is capable of making year after year. Month of Diwali is different from a normal month and is therefore not treated the same way.
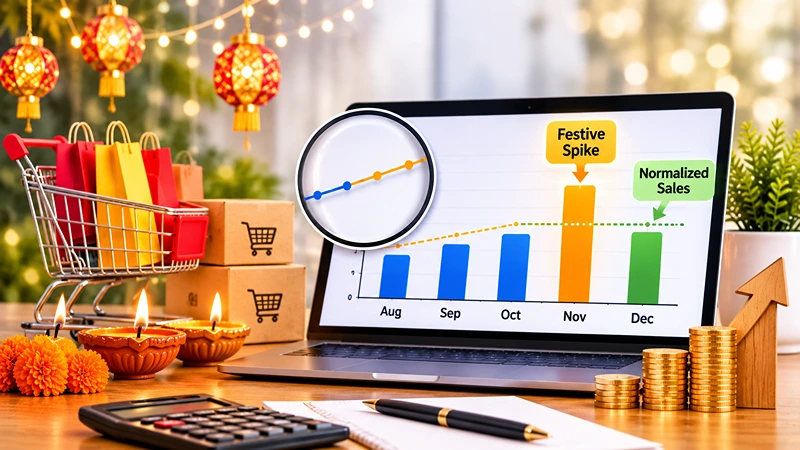
In categories like apparel, jewellery, gifts, home décor and electronics, the festive window can carry off a major chunk of annual revenue. Two mistakes show up again and again:
- Annualising the peak. Take the best festive month, multiply by twelve, and you’ve valued a business that doesn’t exist.
- Throwing the peak away. Some people play safe and use an average month. Now you’ve undervalued a business that really did earn that money.
Normalization sits in the middle. Whether you need a business valuation for a fundraise or for a sale, the goal is the same. Show what a typical, repeatable year looks like, and keep the festive season in it at its true size.
2. How to Analyse Monthly Sales Data Before Valuing Your Business
Annual totals hide everything. Ask for 24 to 36 months of monthly revenue, gross margin and EBITDA, and put them side by side.
You want to see three things:
- How big the festive hump is compared to a regular month
- How quickly sales drop after it
- Whether the non-festive months are growing on their own
That last one matters a lot. If the rest of the year is growing, buyers relax. If the whole growth story lives in October and November, expect questions.
3. How to Identify One-Off Revenue and Costs in Festive Sales
Go line by line and ask one thing: will this happen again next year? If yes, it stays. If no, it gets adjusted.
• Discounts and Clearance Sales
Festive discounting is normal for most brands and it will repeat, so leave it in. A deep clearance of old stock to free up space is different. That’s a one-time hit to margin and should be adjusted.
• Bulk and Corporate Gifting Orders
One big B2B gifting order from a single client can add a few crores in a week. If that client comes back every year, keep it and show proof. If it was a one-time thing, take it out.
• One-Time Marketing and Operating Costs
A celebrity campaign, a big marketplace sale push, extra temporary staff. Some of these come back every year and some don’t. Be honest about which is which.
One warning here. Don’t clean only the revenue side. If you remove a one-off sale but leave the one-off cost that came with it, or the other way round, the normalised number is wrong.
4. Why Normalised EBITDA and Contribution Margin Matter in Valuation
Revenue during festive seasons typically brings about thinner margins. The reason being that the volume discounts are bigger, advertisement costs spike as everyone wants to get the same exposure, speeded up delivery has an increased rate, and gift box packaging ends up increasing the cost.
If we make an assumption that a ₹1 crore revenue at a 15% contribution margin has a very different implication compared to it at 35%.
Track your contribution margin on a monthly basis, and take the decision of valuation relying on normalised EBITDA rather than reported EBITDA.
As a D2C brand, there is an aspect other than sales to consider. Your brand name, your customer list, and repeat buyers are all intangible assets which have great value. A festive sales surge may make all of these aspects seem more robust than they actually are, hence it is recommended that a brand valuation or valuation of intangible assets should also be carried out on normalized figures.
5. How Returns, Inventory and Working Capital Affect Festive Season Valuation
Returns come late. Most festive season orders are returned in the weeks following Diwali, especially in sectors like fashion and electronics. If a mid-November valuation was conducted, that means reported revenue may not accurately reflect the amount of revenue a business can retain.
Use returns from the previous year as a starting point for making changes. Also, keep a tab on the revenue recognition timing before and after the cutoff date.
Inventory is something to be wary of as well. Companies tend to hold more inventory during this season. The remaining unsold stock might even need to be provisioned, particularly the fashion items designed with seasonal patterns that will not go on sale when a new spring season starts in March.
And working capital, of course. Diwali brings about the huge fluctuations in Payables and marketplace receivables. To avoid an odd net debt and working capital figure, it might be better to look at the average over a 12-month period rather than the balance on one day as a starting point.
6. How Diwali Timing Changes Your Trailing Twelve Month (TTM) Numbers
Diwali dates vary sometimes it’s in October, other times in November. Hence, if your trailing twelve month window includes the festive period, you have at the minimum a half a season or at the maximum one and a half seasons or even two.
Be consistent. Either stick with full year financials or use a trail of twelve months that covers only one complete festive season. Compare apples to apples. Dhanteras, Navratri and various sale events also fluctuate from year to year, so be sure to double check those dates too.
This timing issue shows up in employee stock options as well. If you grant options right after Diwali on inflated numbers, the ESOP valuation comes out higher than it should, and your team ends up paying a higher exercise price for it.
7. Best Valuation Methods for Retail and D2C Brands After the Festive Season
Once the numbers are cleaned up, the method is easier to choose.
- Market multiples: Apply them to normalised trailing revenue or EBITDA. Never to the festive peak.
- DCF: Build a monthly forecast with seasonality in it, then roll it up. Don’t assume the festive growth rate keeps compounding. Proper financial modeling and forecasting takes care of this.
- A simple bridge: Show reported EBITDA, each adjustment, and normalised EBITDA. Investors and auditors both like seeing it laid out.
Here’s a made up example. Say a D2C brand reports ₹5 crore EBITDA. ₹80 lakh of that profit came from a one-time corporate gifting order, and ₹30 lakh of one-time campaign spend is sitting in the costs. Normalised EBITDA comes to ₹4.5 crore. At a 12x multiple that’s ₹54 crore against ₹60 crore. Same company, ₹6 crore apart, only because of the clean-up.
Where the number ends up matters too. If you’re raising money through CCPS or CCDs, the convertible securities valuation depends on these same normalised figures. If a foreign investor is coming in, FEMA valuation rules need a number you can defend. And if you’re buying or selling a brand, mergers and acquisition valuation starts from the same clean base.
8. Festive Sales Normalization Checklist: A Quick Summary
Quick checklist before you share numbers with anyone:
- Pull 24 to 36 months of monthly data
- Mark every one-off, on both revenue and cost
- Check contribution margin for the festive months
- Adjust for returns and unsold stock
- Use average working capital, not a single date
- Match the valuation period to one full festive season
- Show a clear bridge from reported to normalised EBITDA
Why Choose ValuGenius for Retail and D2C Business Valuation in India
Normalization is where most of the real work in a retail valuation happens. This is not done through formulas only but requires judgments based on human knowledge.
At ValuGenius, we sit down with your finance team, dig into the monthly data, separate the recurring items from the one-offs, and deliver a robust valuation report you can confidently defend in front of investors, auditors, or buyers.
If you’re planning a fundraise, a business sale, or an ESOP grant after Diwali, it’s worth getting the numbers right from day one.