Pre-Money vs Post-Money Valuation: What Founders Must Understand Before Raising Capital
Founders often get asked a single question very soon after beginning their fundraising process: What will be your valuation?
Someone will most likely then inquire, “Is that the pre-money or post-money valuation?”
Much more can happen due to that single word which determines the ownership, investor’s share, and the amount left with the founders post-funding.
Everyone gets confused by this issue. A founder might overhear an investor saying that, ‘We wish to put in ₹2 crore of our capital for ₹10 crore valuation.’ Seems pretty understandable until you dig deeper and check whether the valuation of ₹10 crore mentioned is that which was before or after the investment in question. That sounds clear until you ask whether the ₹10 crore is before or after the investment.
What Is Pre-Money Valuation?
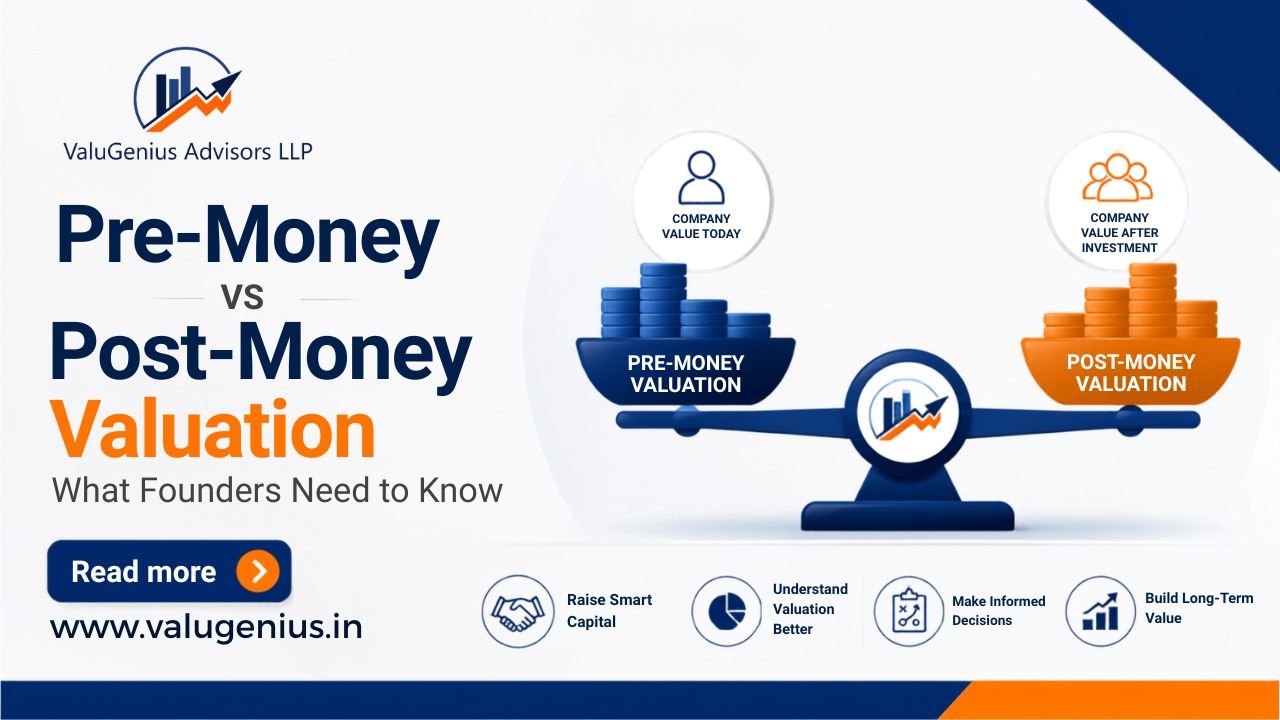
Pre-money valuation is the agreed value of the company before new investment enters the business.
If an investor offers ₹2 crore at a pre-money valuation of ₹8 crore, the company is being valued at ₹8 crore before the round. After the money comes in, the post-money valuation becomes ₹10 crore.
Pre-money valuation is usually the number founders negotiate with investors. It reflects the company’s current position, future potential, market, revenue, growth, team, and the level of interest in the round.
In practical terms, pre-money valuation is the value assigned to a startup before new outside financing. For early-stage businesses, the discussion can include comparable companies, the founding team, market opportunity, traction, and investor demand because the financial history may still be limited.
Simple formula:
| Post-money valuation = Pre-money valuation + New investment |
What Is Post-Money Valuation?
Post-money valuation is the company’s implied value after the new investment is added.
The relationship is straightforward: post-money valuation is the pre-money valuation plus the new investment in a priced round.
So if the pre-money valuation is ₹8 crore and the investor puts in ₹2 crore:
- Pre-money valuation: ₹8 crore
- New investment: ₹2 crore
- Post-money valuation: ₹10 crore
In a simple priced round, the investor’s ownership is calculated by dividing the investment by the post-money valuation.
| Investor ownership = Investment amount ÷ Post-money valuation |
In this example, the investor would own 20% because ₹2 crore is 20% of ₹10 crore.
That is the basic math. The final cap table can change when an option pool, existing convertible instruments, or other rights are included in the round.
A Simple Example With Numbers
The next table is a different scenario from the earlier ₹8 crore pre-money and ₹2 crore investment example. Here, the headline valuation stays at ₹10 crore, and we change only whether that figure is before or after the investment.
| Offer in the term sheet | Implied post-money valuation | Investor ownership | Founder ownership after the round |
| ₹2 crore at ₹10 crore pre-money | ₹12 crore | 16.67% | 83.33% |
| ₹2 crore at ₹10 crore post-money | ₹10 crore | 20.00% | 80.00% |
The investor writes the same cheque in both cases. The difference is the ownership percentage attached to that cheque.
Now imagine the startup has two founders who owned 50% each before the round. In the first scenario, each founder would hold about 41.67% after the investment. In the second, each would hold 40%.
The numbers look close. Across several rounds, those differences can become meaningful.
This is why founders should ask for the pro-forma cap table, not rely only on the valuation headline.
How the Terms Change Founder Ownership
The Headline Valuation Changes the Percentage Sold
The pre-money or post-money label changes the amount of ownership the investor receives for the same investment. A higher pre-money valuation generally means a smaller percentage sold in that round. A lower pre-money valuation means the investor receives more equity for the same capital.
The comparison above shows the point faster than a long negotiation discussion. Always write down the investment amount, the valuation basis, the implied post-money value, and the investor’s percentage in the same place.
The Option Pool and Existing Convertibles Matter
Investors often ask founders to create or increase an employee option pool before the funding round closes. The pool is meant for future employees and key hires, but the timing affects who bears the dilution.
If the option pool is counted in the pre-money share capital, founders and existing shareholders may absorb most of that dilution before the new investor comes in. A fully diluted cap table includes outstanding shares plus options, warrants, SAFEs, and convertible notes that could become shares later.
Ask for the cap table before and after the option pool, and include every outstanding instrument in the model. The number that matters is the ownership everyone will have after the round, not only the shares issued today.
Investor Rights Can Change Exit Outcomes
Valuation is important, but it is one part of the deal. The investor rights in the term sheet can affect what founders and employees receive in a sale or down round.
- Liquidation preference: Preferred investors may be paid before common shareholders in an exit. A 1x non-participating preference usually gives the investor a choice between getting the preference amount or converting to common. A participating preference can let the investor receive the preference and then share in the remaining proceeds.
- Preference stacking: If preferences are stacked, later investors may be paid before earlier investors. That changes the order in which exit proceeds are distributed.
- Anti-dilution protection: In a down round, the preferred investor’s conversion price may adjust so the investor receives more common shares on conversion. Full ratchet protection uses the new lower price, while broad-based weighted-average protection makes a smaller adjustment based on the size of the round and the company’s capitalization.
- Control rights: Board seats, veto rights, protective provisions, and pro-rata rights can affect future decisions and future fundraising.
A ₹10 crore post-money valuation with heavy investor rights may not be better than a slightly lower valuation with cleaner terms. Read the valuation and the rights together.
Pre-Money and Post-Money SAFEs
SAFEs and convertible notes are often used before a priced equity round. In these instruments, the investor may receive a valuation cap, a discount, or both. The shares are issued later when the instrument converts.
A pre-money SAFE and a post-money SAFE can produce different ownership results because they handle later investments and the ownership calculation differently. The cap table can look comfortable today and change sharply when several instruments convert at the next priced round.
Before signing, ask for a fully diluted cap table that shows:
- Existing founder and investor holdings
- The new investment
- All outstanding SAFEs and notes
- The proposed employee option pool
- Conversion assumptions
- Ownership after the round
If the investor’s percentage is based on a post-money cap, ask exactly what is included in that calculation. The answer should be clear in writing.
What Founders Should Check Before Signing
Before accepting a funding offer, sit with your finance advisor, lawyer, or valuation professional and walk through the numbers slowly.
| Founder funding-round checklist
1. Is the quoted valuation pre-money or post-money? 2. What percentage will the new investor own after closing? 3. Is the investment amount the full round or only the lead investor’s cheque? 4. Is the option pool included before or after the investment? 5. Are existing SAFEs, notes, warrants, or convertible instruments included? 6. Is the ownership percentage calculated on a fully diluted basis? 7. What happens to founder ownership after the next expected round? 8. Do the liquidation preference and anti-dilution terms match the stage and size of the company? 9. Are the board, veto, and pro-rata rights reasonable for the deal? |
A simple cap table review can show the real impact of a deal much faster than a long valuation discussion.
Why Choose ValuGenius?
ValuGenius Advisors LLP is a Mumbai-based valuation and financial advisory firm supporting startups, SMEs, corporates, and investors with startup valuation, fundraising analysis, FEMA valuation, Ind AS valuation, M&A valuation, and financial modelling.
Final Thoughts
Pre-money is the company’s value before the new investment. Post-money is the pre-money value plus that investment. In a straightforward priced round, the investor’s percentage is usually based on the post-money figure.
The part that needs more attention is everything around the headline number: option pools, SAFEs, notes, conversion terms, liquidation preferences, and anti-dilution rights.
Before you sign, ask for the fully diluted cap table. Check the ownership percentage. Read the investor rights. Make sure you understand how much of the company you and your co-founders will own after the round.
A funding round should give the business room to grow. It should also leave the founders clear about what they are giving up.
| Disclaimer: This article is for general information only. It is not legal, tax, investment, or financial advice. Funding terms differ from one transaction to another. Founders should review the term sheet, cap table, and transaction documents with qualified legal and financial advisors before signing. |